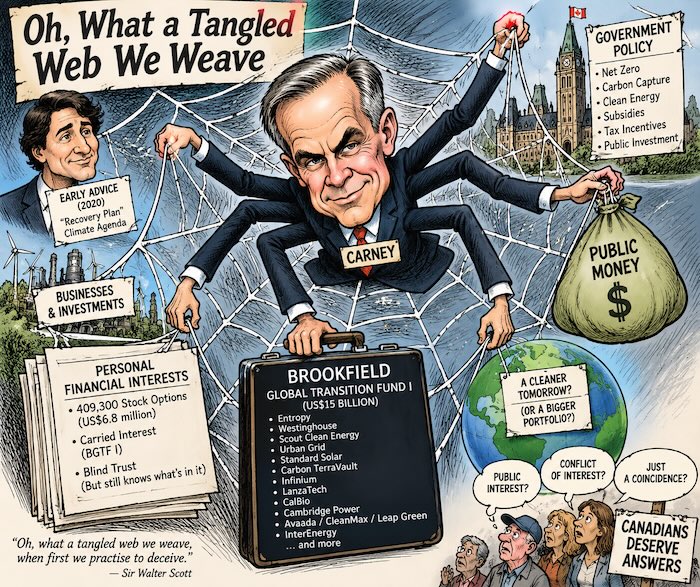
None of that establishes wrongdoing. Governments routinely use tax incentives, guarantees and public investment to encourage private capital. But another thread remains. When Carney left Brookfield, he did not sever every economic connection to its transition investments. Parliamentary testimony subsequently discussed his entitlement to carried-interest payments from BGTF I—deferred compensation linked to the performance of the fund.
Then there are Carney’s options on Brookfield. At December 31, 2024, Brookfield disclosed that Carney held 409,300 unexercised Brookfield Asset Management stock options: 209,300 exercisable at US$35.13 and 200,000 at US$40.07. Their combined intrinsic value was US$6,813,892. They carried expiration dates in 2033 and 2034. Options are important because their value changes with Brookfield's share price. They are not merely a record of what someone was paid years ago; while outstanding, their economic value can rise or fall with the underlying shares.
Meanwhile, Carney's political involvement was becoming increasingly formal. In September 2024, the Liberal Party appointed him chair of the leader's economic-growth task force. Months later Trudeau resigned, Carney entered the leadership contest, won, and became prime minister.
His investments were subsequently subjected to conflict-of-interest arrangements, including a blind trust and an ethics screen. Yet a blind trust presents an interesting problem when the beneficiary already knows what went into it. It may prevent him from knowing what a trustee subsequently buys or sells. It cannot erase his knowledge of the businesses, investments and strategies with which his financial interests had been associated.
That leaves Canadians with legitimate questions. When government policy encourages carbon capture, nuclear energy, renewable power, batteries and sustainable fuels, do investments associated with BGTF I benefit? When public money, tax incentives, or guarantees improve the economics of those industries, can that ultimately affect the value of Carney's deferred carried-interest entitlement? And what is the present status of those 409,300 Brookfield options?
These facts do not establish corruption. Policy overlap does not establish improper motive. Nor does a profitable investment demonstrate that a government decision was made to benefit its investors. But that is precisely why transparency matters. Canadians should not have to choose between accusations and assurances. They should be able to follow the money, examine the relationships and judge the evidence themselves. When political power, public money, private investment and personal financial interests become woven together, sunlight is not partisan. It is simply good government.