What My Junior High School Science Teacher Taught Me About Health Care Reform
Fast-track insurance reform. We can rebuild the health insurance pricing and acquisition process from the ground up in less than 20 months
Guest Column Mark R. Goldstein, Bio and Archives--January 24, 2010
Cover Story | Comments | Reader Friendly | Subscribe | Email Us
If you have a broken piece of equipment or system, and an ignorant, arrogant repairman shows up to fix it, you'll get a temporary repair. However, in accepting an arrogant Insurance Reform Bill, do we not inherit an expensive, national, multiple Dot.com crash-like accident looking for a place to happen?
Call this a message from a mentor. It seems that our legislators rushing headlong towards an immediate solution, can't see the forest for the trees. Everyone needs to learn two very powerful lessons. The first lesson: We have proven web-based technology, coupled with government resources that can achieve fast-track insurance reform. We can rebuild the health insurance pricing and acquisition process from the ground up in less than 20 months. To achieve that goal, self-serving insurance legislation will have to take a back seat to common sense. In a genuine insurance overhaul, public & private purchasing would take the direction of airline travel, with web-based Priceline, Expedia and Travelocity type agencies displaying multiple insurance products on a web-page, as they do travel destinations. Buyers could send discounted policy bids to insurance companies, as they do airline tickets and hotels. Private, Cooperative & Government-run health plans would work as similar product competitors, putting politics aside. To the insurance buyer, Government-run, Private and Coop health plans, would be just airline destinations. Our legislators have purposefully ignored the fact that we are at war for preservation of the American way. Back in 2000, Dot.-Com crash ineptness and self-serving arrogance resulted in worldwide investors losing $4.3 trillion in real money. The coming Health Care Insurance Reform crash will cost us more than double that, all owing to Congressional mismanagement of national priorities. In 2014, over 1/3 of families here in the U.S. could go bankrupt, as could the same percentage of small-to-medium businesses, owing to unbearable insurance burdens. It stinks to high-heaven.
The second lesson:
Congress must relearn in advance, an old junior high school science lesson. It can be done at a fraction of the expected tuition. Result: A rebuild could be implemented that is only the augury of a highly conclusive, exciting second American Revolution.The Science Lesson:
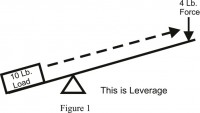
Fifty some odd years ago, I walked into my Junior High School Science class where Mr. Perry, my science teacher, had a placed a mechanism on his desk. It looked like Figure 1, having a 5 foot long board that was balanced on a triangular piece of metal (a fulcrum). He placed a 10 pound weight on the board to the left of the fulcrum causing the board to the right of the fulcrum to rise.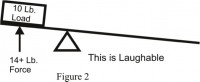 He placed a 4 pound weight on the board, slightly to the right of the fulcrum. Nothing happened. He removed the weights and pulled the board to the right, as shown in Figure 1, creating a short end to the left of the fulcrum. He, replaced the 10 pound weight on the short end to the left, causing the board length to the right of it to rise again. This time, he placed the 4 pound weight slightly to the right of the fulcrum, sliding it along the board length, further and further to the right of the fulcrum, reaching a point where the 10 pound weight to the left of it began to rise. Imagine that. He explained that miracle to us as being leverage, an intelligent way of mastering a challenge. "If you had a 1,000 lb. weight on the short end of the fulcrum, and the same length board, you could raise it with less than a 400 lb. force. The rule would remain consistent.
 Mr. Perry then removed the 4 pound weight causing the short end of the fulcrum to slam down to the top of his desk. He went to the short end of the fulcrum, as Figure 2 illustrates, and pretended to strain himself lifting the load from that end. It was obvious to us that he was acting in a highly inefficient manner. "Don't try this at home," he said, winking at us. We laughed "With him," in both our teenage arrogance and innocence, realizing that his point had been made. Mr. Perry had reminded us that there was both a smart or dim-witted way to get any job done without the hysterics that politicizing embraces.
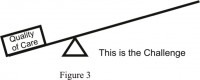
Which brings us to Health Care Insurance Reform (Figure 3). Nothing has changed since our experience in Mr. Perry's Junior High School Science class. The insurance companies, their lobbyists, Congress and others would have you believe that the laws of physics have changed. Their arguments are made by groups of arrogant, dim-witted, and selfish people from both sides of the aisle. Mr. Perry would explain their dishonest behavior in the following fashion: The challenge, the newly-emerging weight to be lifted, is mastering Affordable Quality of Health Care for both business and the American Public. Even here, the rules remain consistent.
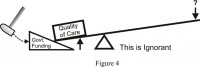 Figure 4 presents an interesting observation; a Government attempt to wedge up the health care load from the short end of the fulcrum. Our lawmakers came up with "A Brilliant Idea." They took a piece of shim stock (the pending Government Insurance Funding Health Care Legislation) and hammered it under the board's short end in an attempt to wedge the load up. Intelligent observers ask: Why don't we instead apply a lesser force to the right-most end of the fulcrum? The decisive question: Just what do we call that lesser force?
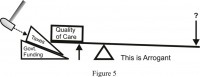 There's more to this scenario. Figure 5 presents a next questionable action. Discovering how much a foolhardy lifting of the Quality of Care load at the short end of the fulcrum will cost, our lawmakers then moved to create legislation (another piece of shim stock) that they would hammer in under the load in an attempt to further wedge it upward. That legislation would tax the American public in order to raise the funds needed to do what a classroom of junior high school students had laughed at Mr. Perry for attempting some 50 odd years ago. The concept of pushing down on the long end of the fulcrum was again brushed aside as nonsense, but by whom? Hey, you can get away with this stuff by telling the American public that you are only going to tax rich people, and by the way, you are the party in power, so there is nothing that the American public can say about it anyway! The result: Protests!
The special interests, the insurance lobbyists, executives & politicians who are in the insurance executives' back pockets would have Americans believe that all of this is theory, that in effect, there is neither a fulcrum, nor long right end of the board. Theory is supposition; this is Theorem, a proven fact. Theorem is purchasing leverage - airline ticket purchasing power, the buying power due the American People through similar systems. Insurance buying cooperatives & Government-run options are just new competitive product entries. We need a paradigm shift, a massive rule breaking, a re-pricing of American insurance premium and buying systems, the first step in the revolution.
Bureaucrats, Bean-Counters & the Force to the Right of the Fulcrum:
Politicians from both sides have a nasty tendency to stand up in public, making tactless references to "Bureaucrats and/or Bean-counters," people supposedly to blame for the failure of a system that these very politicians had a sworn duty to protect. They make defamous statements, while in their minds thinking that the American public is ignorant, and will eat it up. The fact is, that we have discovered that many of our politicians don't begin to know what they are talking about, and they have little interest in learning. Their commentary has always been a "Red Herring," a political, hate based diversion; something that they think they can say in public without being challenged. Well, they used a group of accountants to test the financial solvency of our biggest banks just a few months ago, and their bureaucratic labors produced professional results. It's time to extend that successful auditing model into discovery of a real insurance paradigm, whose discovery is at the foundation of a needed solution.Bureaucrats:
After 40+ years of having dealt with bureaucrats, I can state this with confidence: Police and Bureaucrats are both deserving of riding around in vehicles that have the following message painted on their doors: "To Protect and Serve." Most bureaucrats protect the public with a journeyman's dedication, and their voyage in a re-birthed America is only just beginning. In order to produce leverage for the American people, we have to pass emergency paradigm laws, setting up an office of the National Insurance Commissioner (similar to the SEC) for reasons that I will explain. Under it, a Justice Department team of forensic accountants and actuaries, "Untouchables," will be dispatched to all of the insurance companies doing business in the U.S. Their mission: Perform comprehensive operational audits of these companies. For the forensic actuaries; they will be chartered to determine the true risk experience that an insurance company has undertaken in insuring clients for all of the insurance policy types that they have written. The forensic actuaries' findings will be the basis for a reformed "Advice to Premium Pricing," determining fair business costs and respective reasonable premium pricing for all categories of insurance.The task given to the accountants:
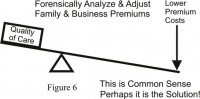 To forensically audit the books, policies & procedures of these insurance companies, and along with forensic actuary input, determine what is the reasonable costs of doing business and finally, insurance company profit. From that, the forensic accountants could arrive at new reasonable figures for insurance premiums, a necessary practice that we haven't seen since WW II era price control. It would be logical to suggest that these forensic "Bean-counters" would recommend a sizable reduction of many categories of insurance premiums. The mere suggestion of this significant action would bring a hue and cry from members of Congress that would be enormous. These Congressional members are the one's who should be censured and perhaps prosecuted. Wherever Mr. Perry is, he would smile. Figure 6 illustrates that his students have rediscovered the identity of the 4 lb. force at the right-hand side of the fulcrum; a dramatic lowering of insurance premiums.
Congressional members, insurance companies and their lobbiests will tell you that this recommendation is socialism. That argument is also a "Red Herring." Their stonewalling is intolerable and stands in the way of real health and other insurance reform. Years ago, the insurance companies instituted a brilliant strategy. They hired lobbyists to contact members of state and federal governments. The lobbyists convinced our legislators to endorse laws creating mandates governing insurance coverage. In plain language, if you were an individual or business, you would be required to carry certain types of insurance, "Or Else!" If you were a business who didn't carry a certain insurance (i.e. Worker's Compensation), or one who had fallen behind in paying insurance premiums owing to slow cash flow business conditions, an insurance carrier doing business in your state could report you to the State or Commonwealth Insurance Commissioner's Office, and as punishment, demand that it contact the State Corporate Commission or Bureau that licensed your business, and have your business license revoked.
If you were an individual whose automobile insurance had lapsed owing to the fact that you were out of work, and could no longer afford it, an insurance carrier doing business in your state could report you to the State Department of Motor Vehicles, demanding that the DMV cancel your automobile's license and perhaps your driver's license as well. The insurance company's argument was flawless: "Government has to protect the public from dangerous organizations & individuals, not carrying enough insurance on themselves." To hear them speak, every business not paying their premiums on time was criminal; every driver was homicidal, and every doctor/hospital was a butcher.
In Massachusetts they enacted a health care reform system, a mandate. You had to carry health insurance, or else! If you were an individual whose health insurance had lapsed owing to the fact that you were out of work, and could no longer afford it, or your income didn't allow for you to purchase it, what could an insurance carrier doing business in Massachusetts do? The Commonwealth could assess fines against you and more. I don't know, but could a person in Massachusetts be refused employment, or lose their job owing to the fact that they couldn't make their insurance premium payments at this time? I'll leave the answer to your critical eye.
Second pass:
Insurance companies decided on a second generation of brilliant strategy. They broke their markets up into underwriting categories. Their plan: In each state, only 1 or 2 insurance companies would offer i.e., worker's compensation insurance to limited vertical markets, i.e. health care, electricians, and plumbers. If you were a hospital and you had worker's compensation insurance, with no loss experience in 10 years, that didn't matter. One day, your insurance carrier would notify you that they were cancelling your insurance "For Underwriting Reasons." When you inquired as to what Underwriting Reasons meant, you were told that your insurance carrier had left the market, but that another insurance carrier was available to insure you (only one insurance carrier for health related employees, where once there had been seven). Immediately, your premiums went up. It was pure supply and demand. They now controlled the supply and could demand whatever premium amount they wished. Your complaint to State Insurance Commissioners over this artificial shortage of carriers earned you this reply: "You should be happy that someone will insure you!" 25-30% of U.S. based businesses will cease their operations over the next four years, if they do not receive reprieve from cartel-style, over-burdensome insurance premiums. Suddenly, being insured has truly become "Protection." If you didn't pay them what they wanted, when they demanded it, insurance companies could use new lobbiest-obtained State Insurance legislation to put you out of business. When Al Capone destroyed businesses and individuals who wouldn't pay protection and he committed other intimidating criminal acts, those actions led to today's RICO laws, but if you have "Friends" in Congress . . . . . . . . A new era was born in which insurance companies could make enormous amounts of money by having campaign fund-accepting "Friends" in State Legislatures and Congress enact laws that would punish and intimidate the American public for whatever reason they chose. The current reform bill contains more of the same, punitive mandates against the insured. Insurance companies have the power; their legal teams have the political contacts. Protesters of this undertaking of racketeering at town hall meetings are called "Thugs" and "Un-American." Congressional tyranny and its support of insurance company racketeering are totally Un-American. What protesters at town hall meetings want to know is what happened to the pursuits of happiness guaranteed to us in the Constitution? It's still there! The states will now have to conduct comprehensive forensic audits of their Insurance Commissioner's operating practices under Federal Insurance Commissioner scrutiny. Those bureaucrats found to be malfeasant in office should be disciplined. There are courageous State Insurance Commissioners who deserve our thanks, but they are too few in number. Free markets result when Insurance Commissioners notify insurers that in order to operate in their state, they will have to offer all of their insurance lines to everyone in that state. We have to reverse the insurance companies' antitrust practices of breaking their markets up into underwriting categories, building web-based free markets with affordable premiums nationwide. Continuous forensic auditing of insurance premiums have to be in place to detect price-fixing and other forms of illegal collaboration. Again, insurance premiums have to be controlled as wartime strategic materials were during WW II. We must investigate that probability!The Other Fellow - My Favorite Subject
On numerous occasions I have called my personal insurance agent to question my insurance premium bill. "I haven't had an accident or gotten a moving violation in years; why are my automobile insurance premiums climbing?" I have called my business insurance agent to question raises in my workers compensation and professional liability insurance premium bill. "I haven't had a claim against these policies since I've been in business. Why are my business insurance premiums so high and rising at a scary rate? They give me two answers: 1) It's not you. You're paying to answer consequences caused by "Other Fellows," and 2) You have to pay these premiums, "Or Else." For 37 years, I searched for the "Other Fellows," with the uninterruptable zeal of Dr. Richard Kimble, as he searched for the "One-Armed Man" in the TV series "The Fugitive." This year, we finally found him, via the AIG bailout. The "Other Fellows," are the insurance executives receiving multi-millions of dollars in bonuses. A Justice Department team of forensic accountants and actuaries would have discovered this, but they weren't in place.Outrageously Punitive Practices:
Businesses who fell behind in paying insurance premiums owing to slow cash flow conditions, had their insurance policy cancelled by their insurance carrier. Upon receiving payment, the carrier would reinstate coverage by placing the business in an assigned risk pool at a punitive increase in premium, as punishment for an unavoidable turn in their business situation. An individual whose automobile insurance had lapsed owing to the fact that they were out of work, and could no longer afford it, received the same treatment. An insurance carrier doing business in their state would cancel their insurance policy, reporting them to the State Department of Motor Vehicles. They would reinstate coverage by placing you in an assigned risk pool at a punitive increase in premium as punishment for this unavoidable turn in your personal life, even though you hadn't been involved in an accident or received a ticket for a moving violation. State Insurance Commissioners' offices have to conduct comprehensive forensic audits of to discover which insurance companies are committing these violations of ethical operating practices in their States, and to reverse these practices . . . now! Health care providers face destruction of their profession from a number of questionable exercises. Doctor's malpractice insurance premiums have become so burdensome that many are leaving their practices. This nation faces a travesty, a physician shortage that will eclipse the nursing shortage by 2012. This abuse requires a major forensic overhaul. The flip answers that our politicians issue: "We'll lose doctors & nurses, but don't worry. We'll import others from outside of this country." Health care providers are victimized in other fashions. The insurance companies are famous for using a system that first "Loses" and then rejects initial invoices for patient care submitted by caregivers, then taking months to finally remit payment to them. This practice is in need of a major forensic accounting investigation, a result of which would lay sizable blame at the feet of a celebrated American. Insurance company, Medicare and Medicaid payment schedules have purposely failed to keep up with the cost of living for health care providers for over 15 years. Now, politicians will severely curb Medicare & Medicaid payments further, to "Reduce Costs." This new message bodes ill for physicians caring for the elderly and those incapable of paying for full care. Actually, some politicians want to eliminate Medicare & Medicaid. These systems work better than current publicity suggests, and the waste, corruption and malfeasance that Medicare & Medicaid are accused of, are for the most part, yesterday's news, given intense auditing that these agencies now perform. Corruption & malfeasance: More easily found in the back rooms of Congress and in private parties held in 5-Star Hotels where the terrifying fate of the American Public has been decided. The elderly paid their taxes and earned their Social Security & Medicare entitlements. The heroes, who stormed the beaches on D-Day and rebuilt this country didn't withhold their courage, stamina and sacrifice. Now, unvetted appointees are examining strategies for withholding later-stage care, not optimizing systems. That does not compute. Employee deductions, withheld for 50+ years, created entitlements that government should not be withholding a second time. It smells of passive euthanasia, regardless of who is offended by that discovery. What they've done with Medicare, they're now doing with Social Security! Let the elderly notify legislators that they will be "Withholding" their support during the next election. The fact is, that what is happening to families and businesses is about to shred the fabric of our society. Only now have the politicians discovered that the last time that Americans across-the-board were this angry, was December 8, 1941. The people who confront their representatives about health care insurance reform, do so in an angry yet well-educated fashion. They aren't members of "Angry mobs," or "Brown Shirts" symbolic of Nazi oppression, as some politicians or special interests would accuse them of. They are part of a new population of victims, truly frightened American families and/or businesses, people, who are at the end of their rope. Our politicians would have them borrow more rope from insurance carriers!Unions:
Of them I have only one thing to say. They are good people who have inadvertently chosen to side with the group selling us "Protection." The protestors are pursuing justice, which has always been the union's mission. The unions are supposed to fight for the oppressed? Exactly what picket line are they marching on? The politicians have thanked the unions, by proposing taxes on their medical plans. The unions have been sucker-punched. Politicians describe our battle for national solvency as a "Tea Party." Our second American Revolution has been brewing in that tea pot, and the tea is now being served to them. Around the world, those both admiring and hating us are frightened at discovering that they made a serious error regarding American ingenuity, toughness and resourcefulness. It's time to correct the grave number of errors made by Congress in legislating health care, automobile dealerships, energy independence, employment, the deficit, and numerous other challenges. On December 8, 1941, no politician stood up in Congress and made tactless references to "Bureaucrats or Bean-counters," people to blame for what had happened one day earlier. We were now at war, and the time had come for us to act as One Nation Under God, Indivisible. There was no room for political maneuvering; no time for campaigning to put the party in power out of power, owing to a tragedy that occurred on December 7th. There was no room for a waste of resources, and surely no room for war profiteering. It did happen, and many of those engaging in such practices were prosecuted, as many today will also need to be prosecuted. Back then, we were at war, and with it came national priorities, including price control. This nation pulled up its bootstraps and its heroic civilian and military population made "Ultimate Sacrifices." Sixty-eight years later, someone is going to decide whether maintaining the quality of these hero's end-of-life is expedient. Today, in an act that totally reverses the rules of war, our representatives elect to punish both an imagined enemy and American citizenry alike! In this new period of American anger, new national paradigm shifts should dramatically break all rules applying to the health care insurance reform crisis and supply new ingenuity & technology-based alternatives. The two most important rules: A) Forget about what political party the President is a member of. This is war, and we need to support him. He, in turn, needs to accept intelligent directions to take in achieving overall insurance reform. Our implementing insurance reforms, has a higher priority than any effort to humiliate his administration, and; B) Our problems are going to require American dedication, ingenuity, intrinsic intelligence and most important, the ability to fight dirty in order to enact a rebuild. Prominent noses are going to be tweaked, with those nose-owners being put out of their office. Everyone fitting that description is only now beginning to realize this. We can't teeter-totter between Republican and Democratic Administrations in our search for the crooks. The idea isn't to remove a bunch of Democrats in next year's election, owing to difficulties that we are having. The idea is to neutralize all of the crooks now! Mr. Perry would have taught us that!An Unalterable Observation
I live in a world of logic and performance. In my world, a designed system or process either works or it doesn't. What differs my crowd from others is that when someone calls us in to fix something that is not working properly or is broken, our job is to diagnose and identify the failure and restore the system to optimum performance expeditiously, to make what is broken today, work again, today. We don't have the luxury of standing back and politically bad-mouthing the Original Equipment Manufacturer. The equipment owner needs immediate restoration of equipment or system performance. I know enough about diagnosis to know that our insurance system is broken, and the immediate failure diagnosis points to an arrogant pretense at fixing it. Life experience has taught me that if you have a broken piece of equipment or system, and an ignorant, arrogant repairman shows up to fix it, you may get a temporary repair. In accepting an arrogant congressional repair, we inherit an expensive, national, multiple Dot.com crash-like accident looking for a place to happen! Foundation-level insurance system repairs have to be implemented first. The principal mission here is protection of the common good of the American public, not an arrogant statement that you are the party in power, so your self-important legislation will be voted in; the American public be damned. The message that the recent health care insurance reform hearings sent to me was that there were too many haughty, injudicious congressional repairpersons from both sides of the aisle involved with the health care reform process. That the majority of Americans were going to get hurt as a result of their actions. I watched Congress spend 1 ¬Ω days arguing that abortions shouldn't be covered by new federal health plans and no time arguing for a forensic accounting & actuarial examination, that would reduce the ultra-high malpractice insurance rates for Obstetric, Gynecological, Pediatric and other doctors, insurance rates that are forcing them to close their practices. You'll have free market insurance, when you eliminate the grandfather handshake deals with state & federal governments that doesn't benefit the public! If health care insurance for a family of four could be adjusted down to $225/month from $725, internet-based marketing ingenuity would eliminate the need for much legislation, but the special interests . . . You know, it was James Carville who taught us the expression: "It's the fairness of the insurance system stupid!" 300,000,000 U.S. citizens have little or no chance when pitted against 4,900 health care lobbyists. The American people are protesting for, good rules without punitive mandates for employers and individuals, who can't afford to insure their families anymore.Tort Reform:
Another attempt to lift from the fulcrum's short end. The Tort Reform that we are being sold is hateful, directed solely against Malpractice lawyers, with little consideration for the victim's financial needs post-malpractice. Tort Reform must strictly address legal restoration of the victim's quality of life, with legal fees being tacked onto the victim's award, not being subtracted from it. How can Congress emphasize Tort Reform, proposing the curtailment of awards (including legal fees), abandoning the victim's future financial needs? That is beyond unconscionable!My diagnostic:
Round up all of the architects and lobbyists involved with the current health care reform package, and we might discover a larger, Watergate-type burglary having been committed against the American public. The insurance companies became good at "Purchasing Statute Enforcement against families & businesses" from Legislators, violating the public common good. Where big government belongs is in regulation and enforcement of the protection of American business & families. In 1958, we were frightened by Russian space accomplishments and managed to put a man on the moon in less than 10 years. Let us be frightened enough of American voter anger to reform insurance in less than 12 months! Public options and cooperatives are part of highly-competitive web-based technology solutions! In 1999, I wrote a major diagnosis and solution, warning the government of the impending Dot.Com crash. The media and the Clinton-Gore administration ignored my warning. This larger diagnosis appears as more than a Junior High School Science Lesson. This terrifying national lesson contains a tough final examination; to reach down and discover our national creativity in order to pass muster on this subject and a host of others related to our ingenuity. Our future solvency is riding on it! © 2010 Mark R. Goldstein All Rights Reserved. Mark can be reached at: markrgoldstein@aol.comView Comments
Guest Column——Bio and Archives
Items of notes and interest from the web.